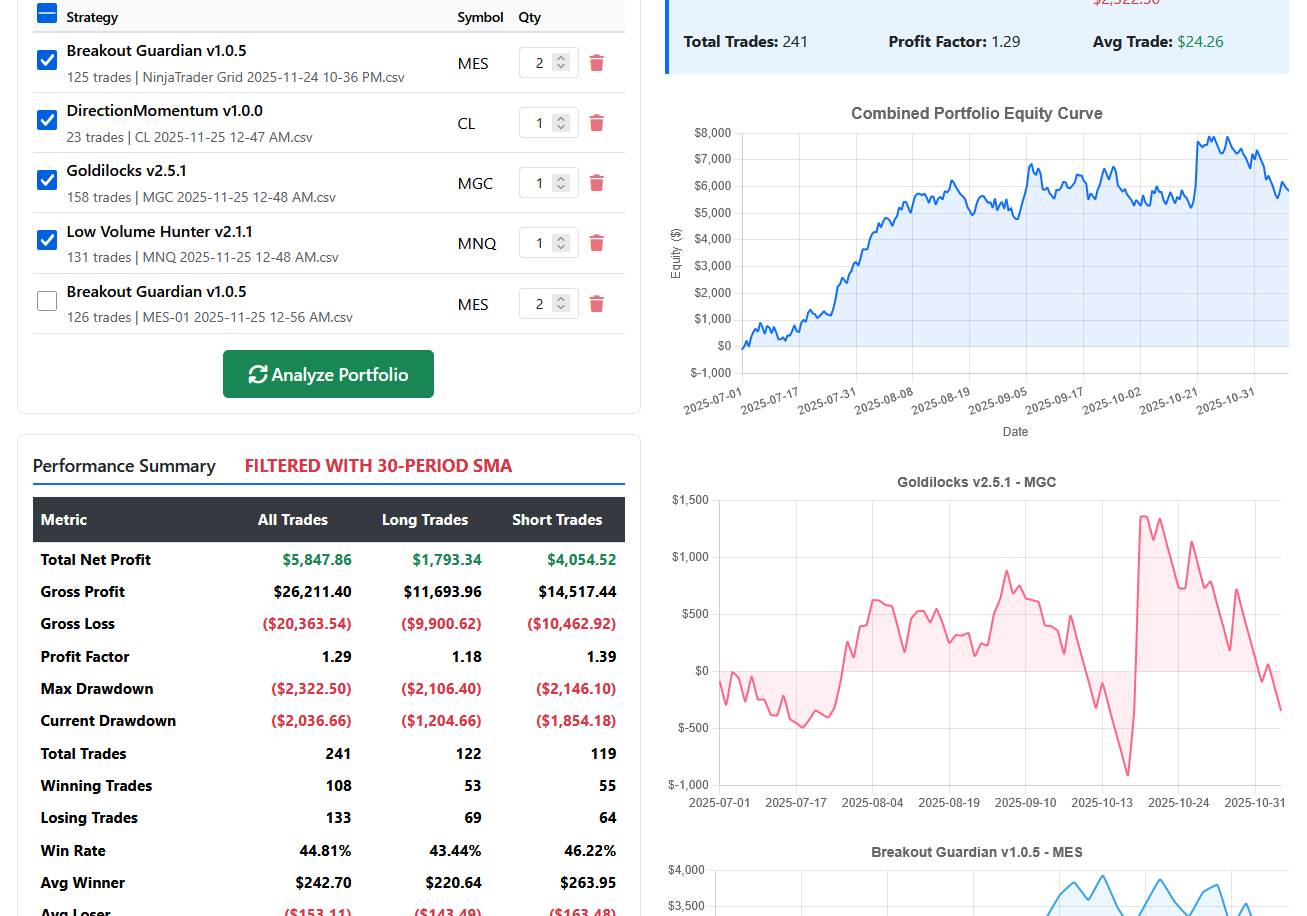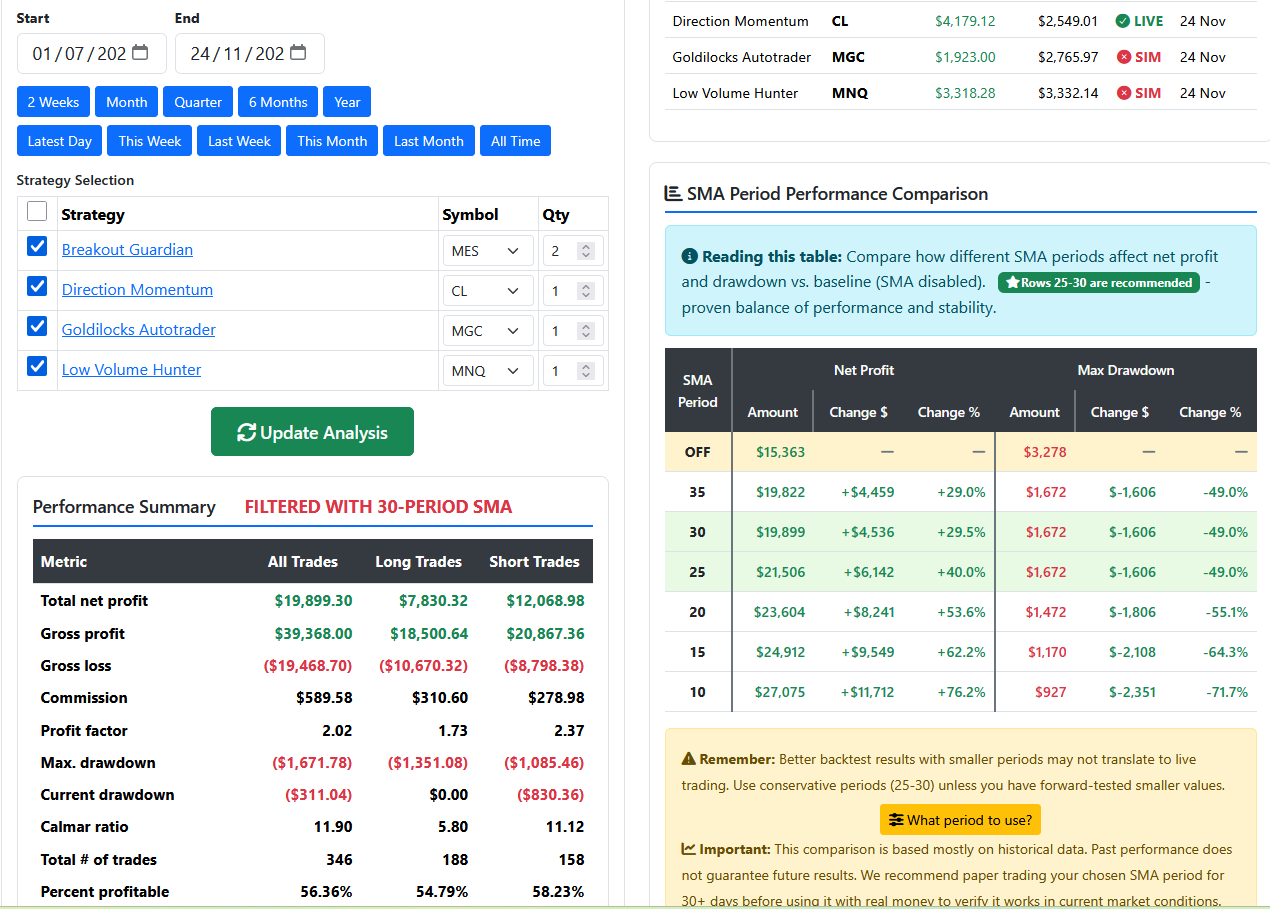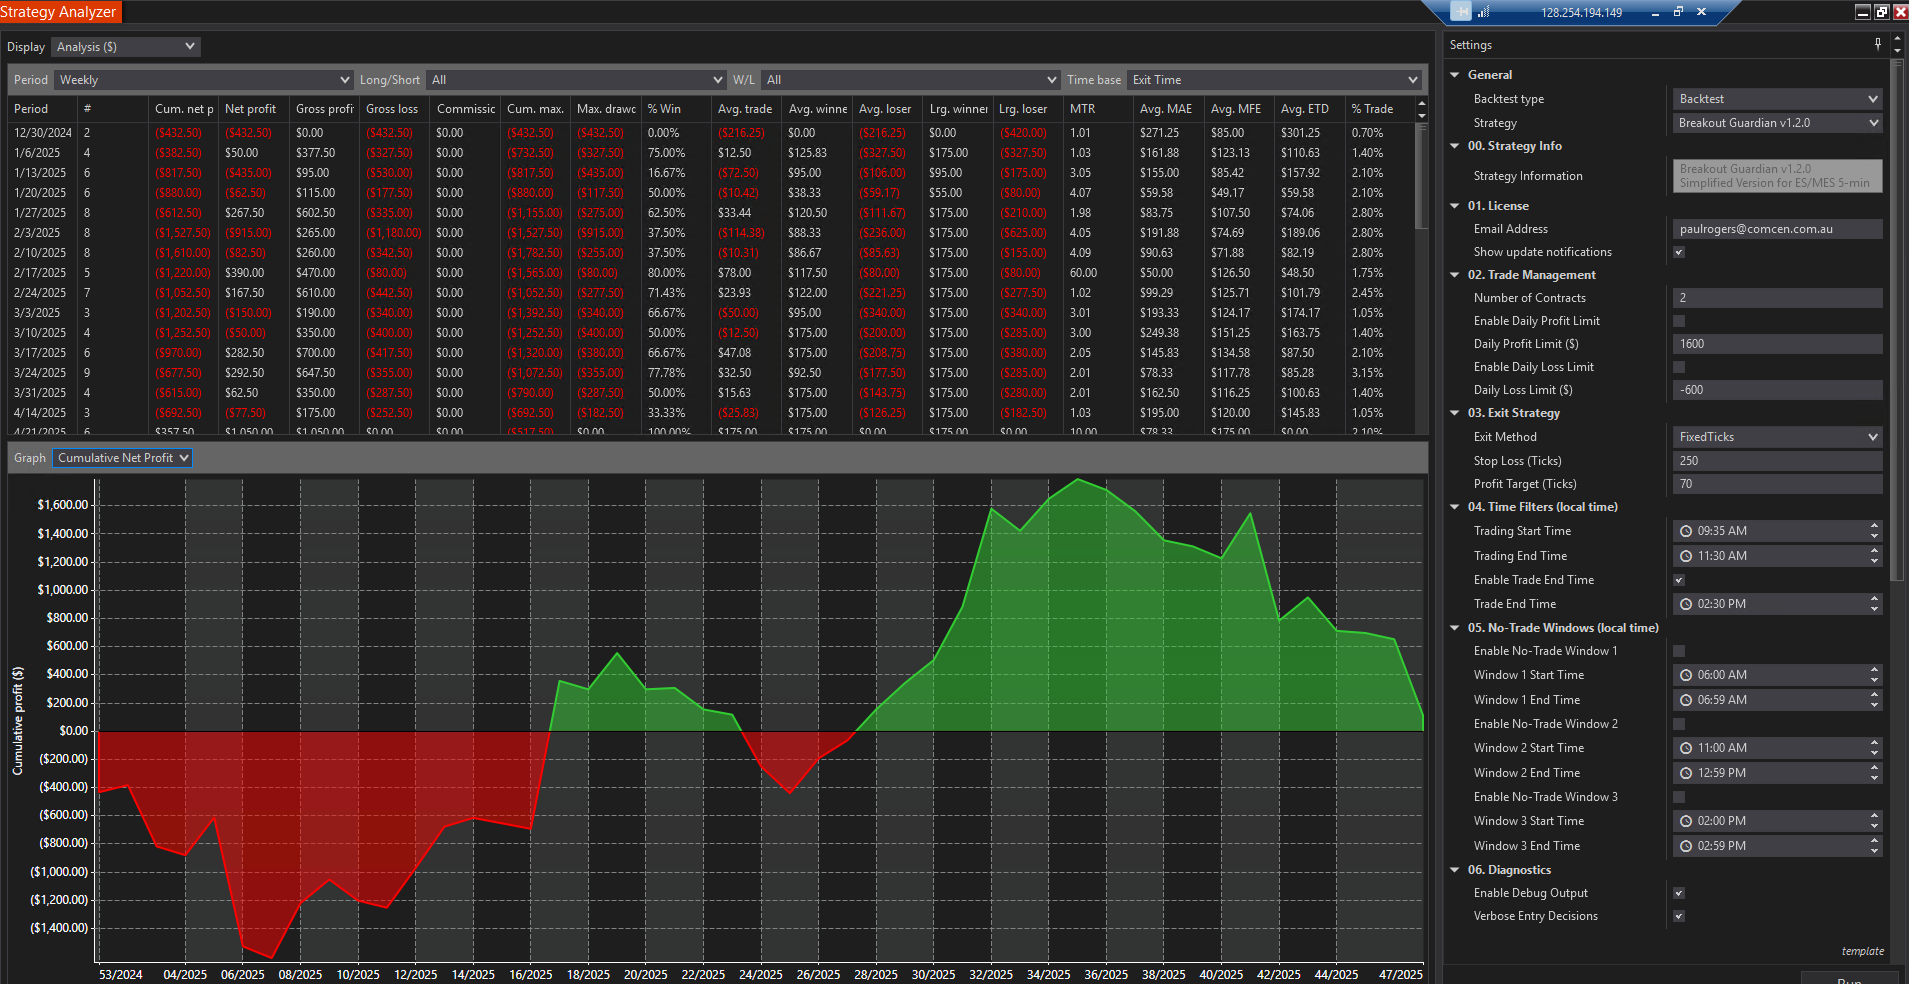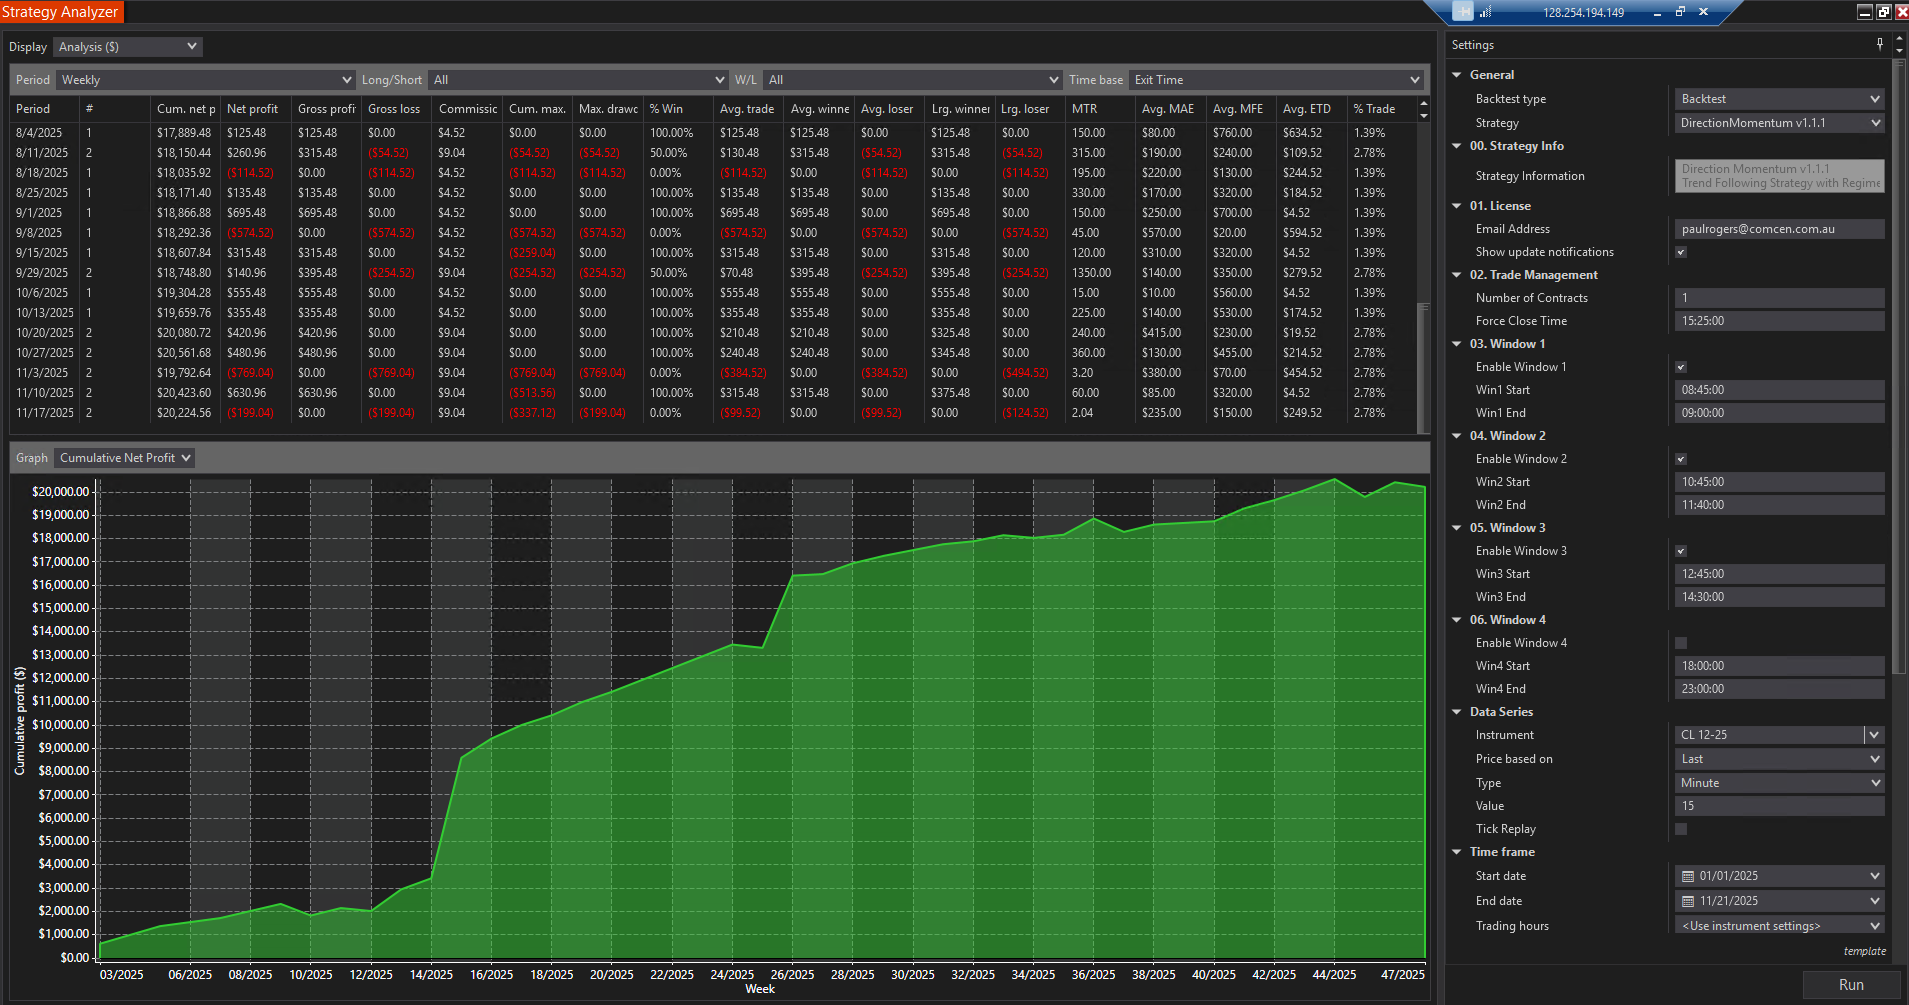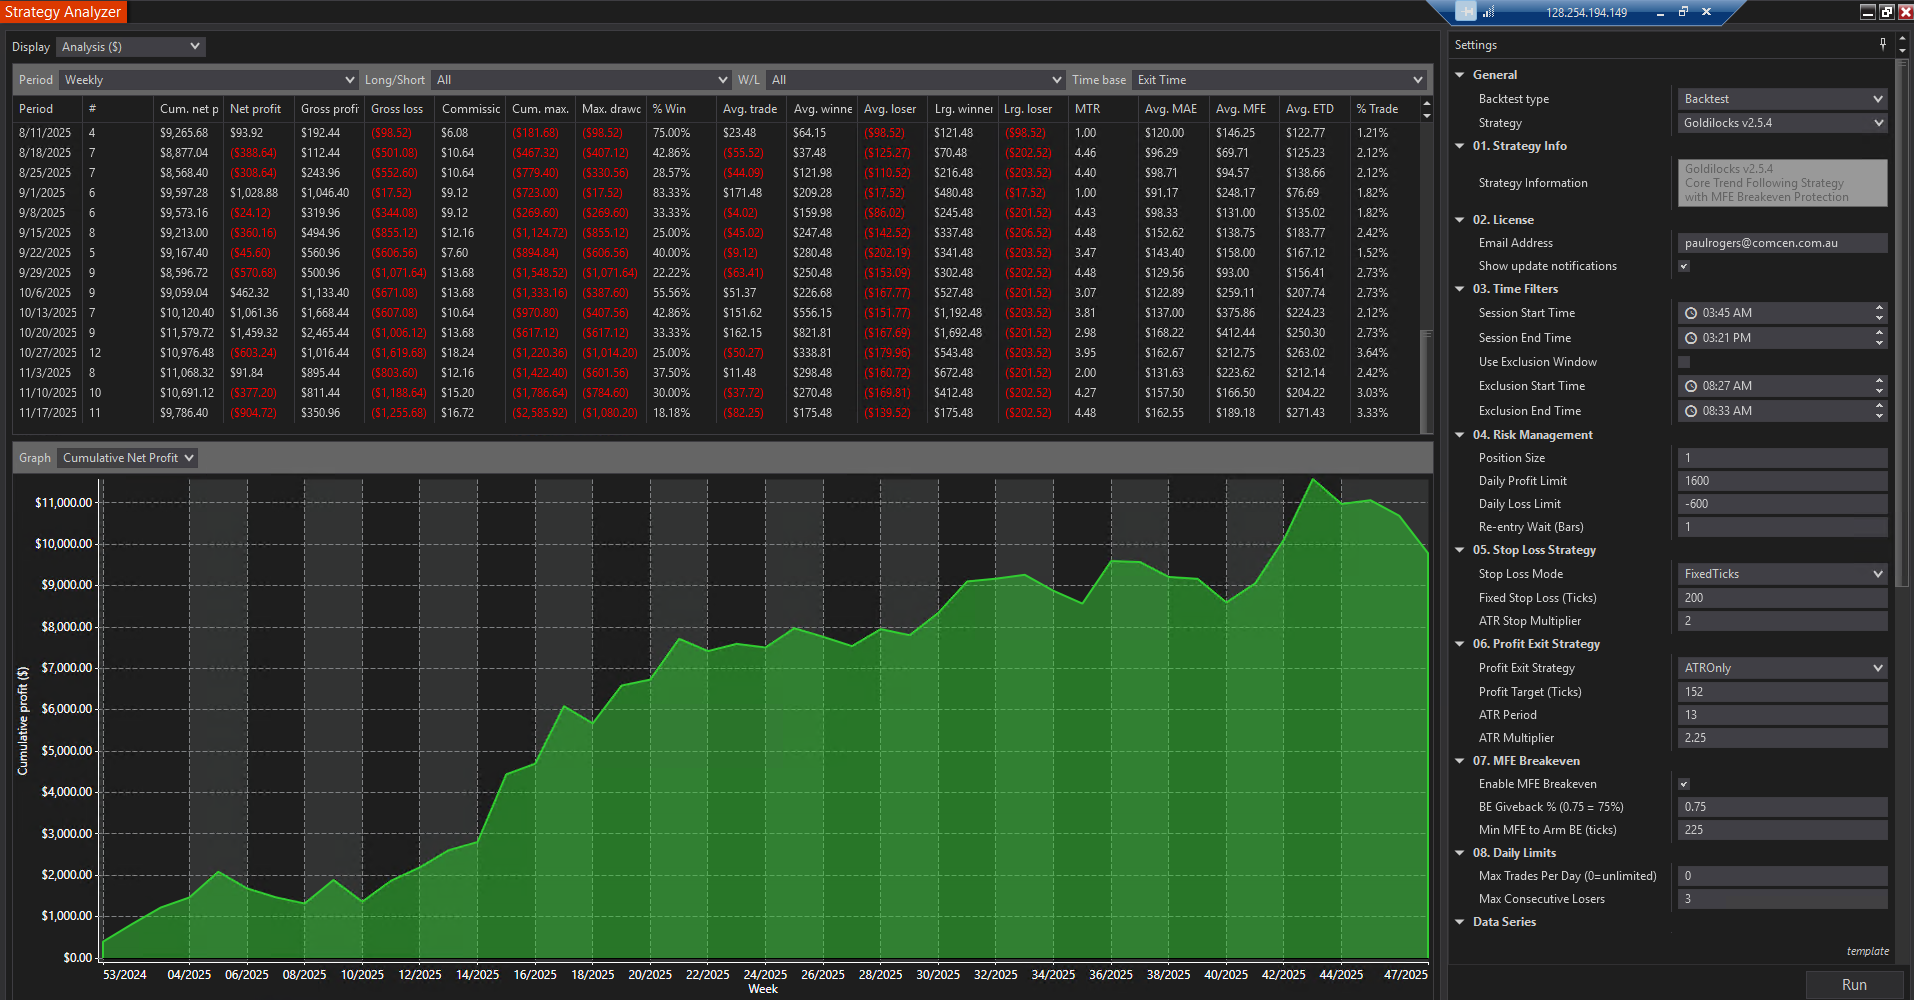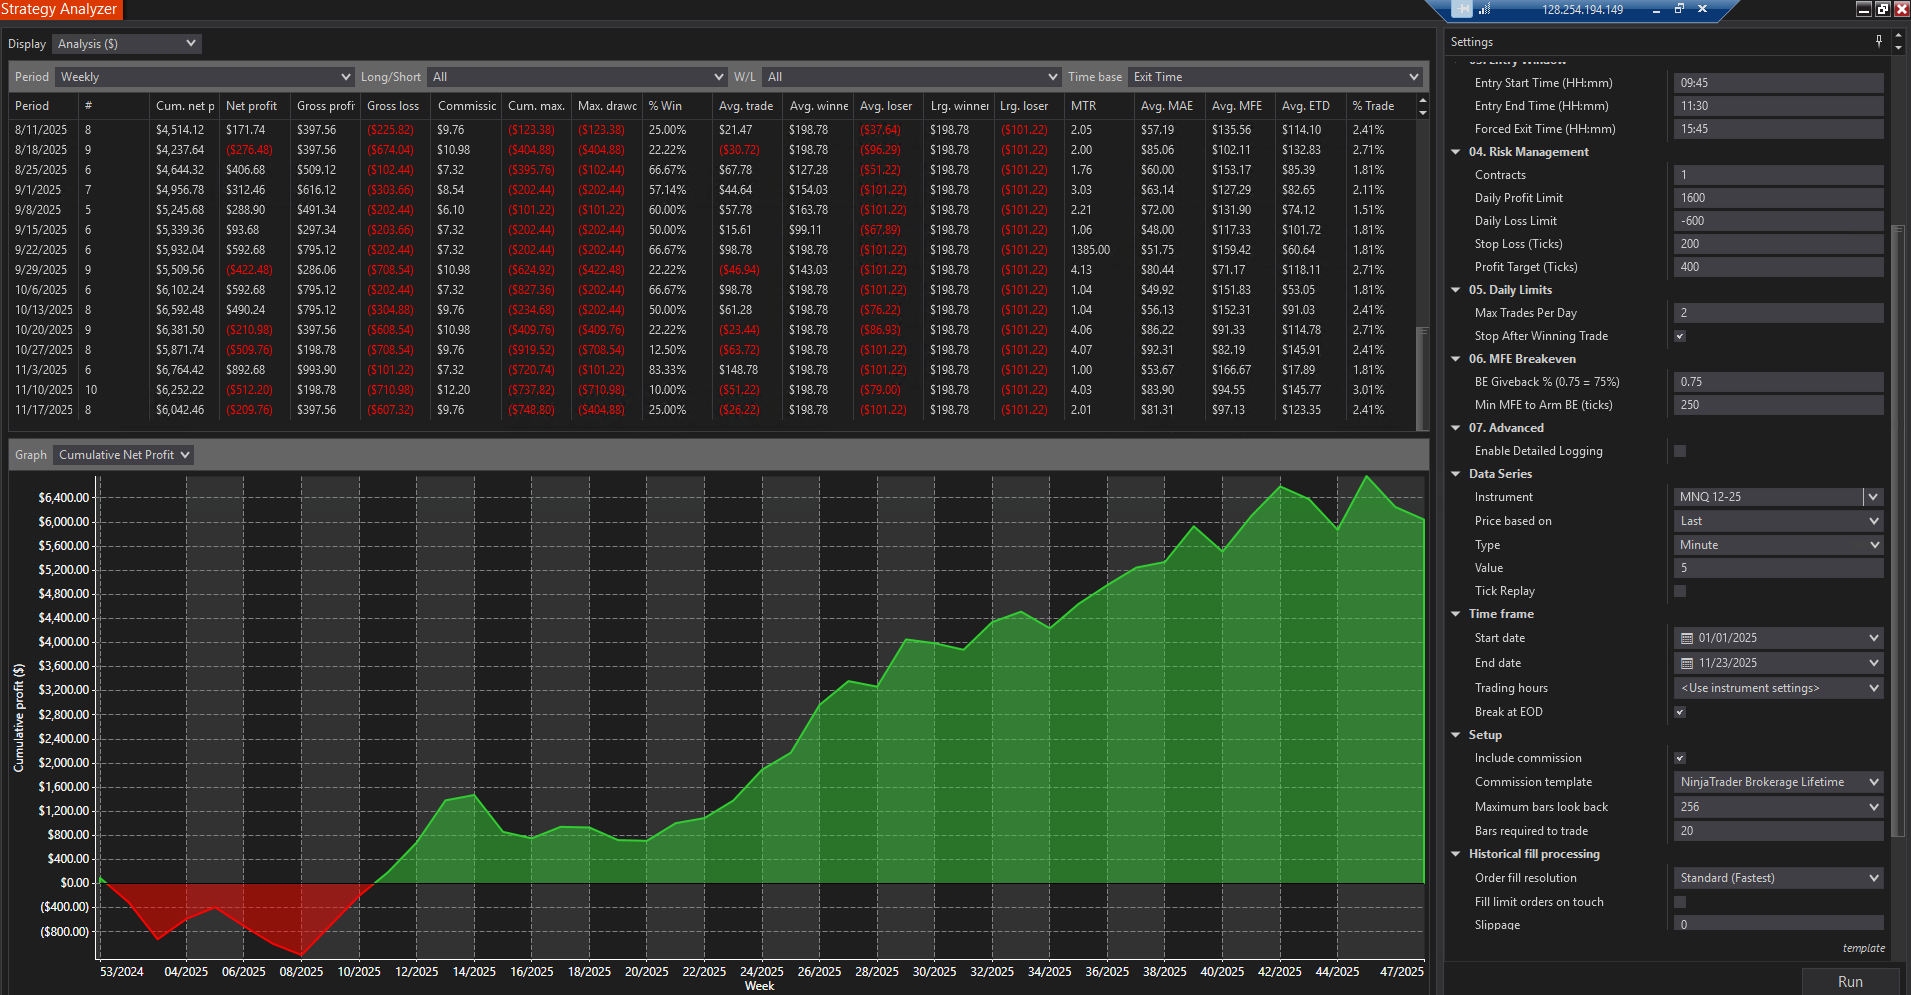
I then started running some back tests in the strategy analyzer. It would give me great confidence in what I have just purchased if I could duplicate something that resembles the results as shown on the website.
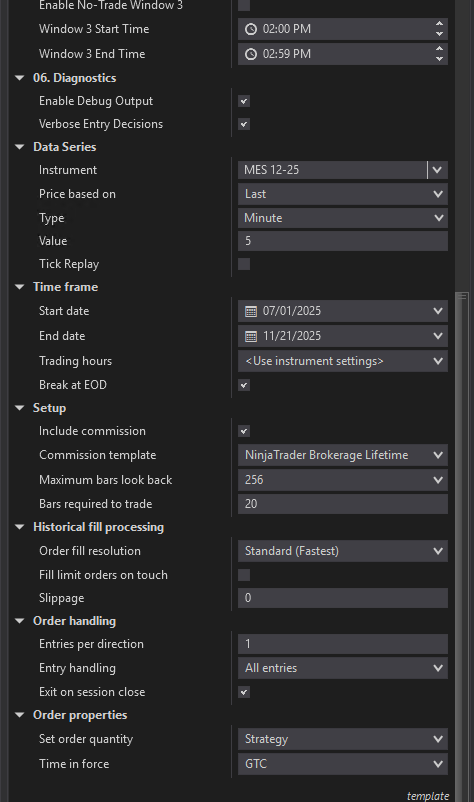
My first question is should I be using tick replay or not? my experience tells me that the most accurate back testing and strategy results usually require tick replay? I understand that strategies can be written in many different ways, but some direction here would be useful please? My results vary greatly from strategy to strategy with / without tick replay.
My NT8 is set to EST, and to keep it easy I am just testing from July 1 2025.
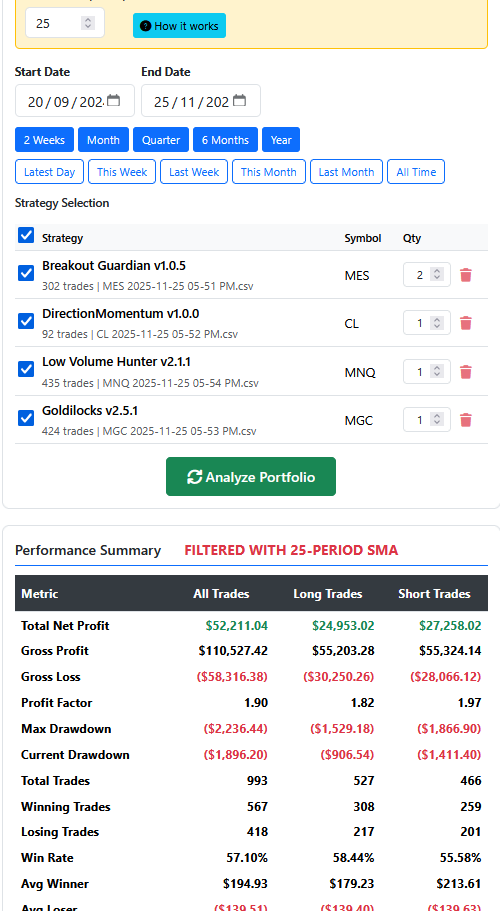
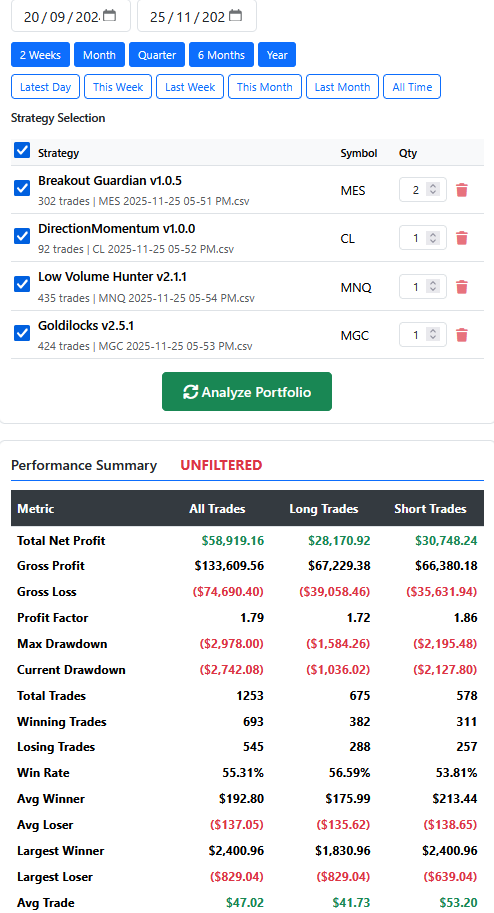
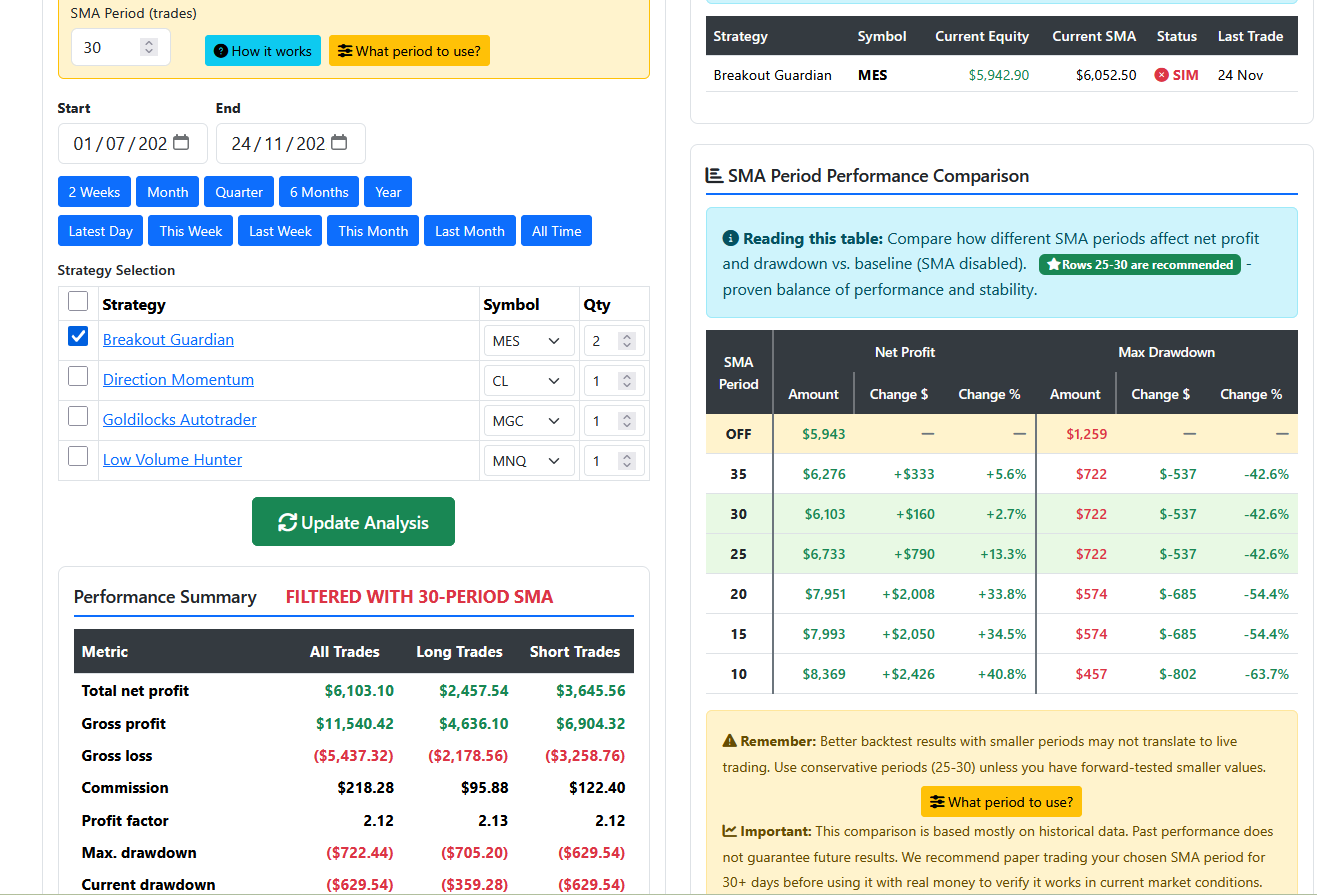
I realized that I also needed to upload the trades to the Portfolio Analyzer and apply a moving average etc. as this has typically been applied to the results etc.
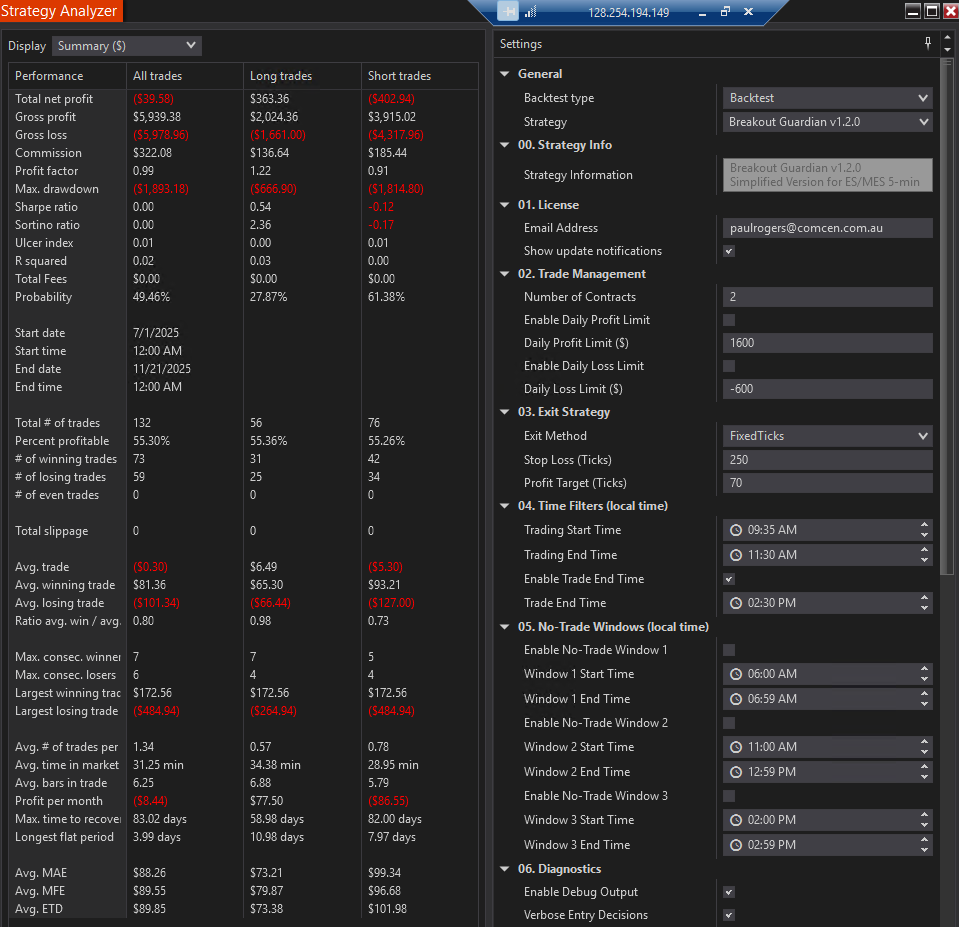
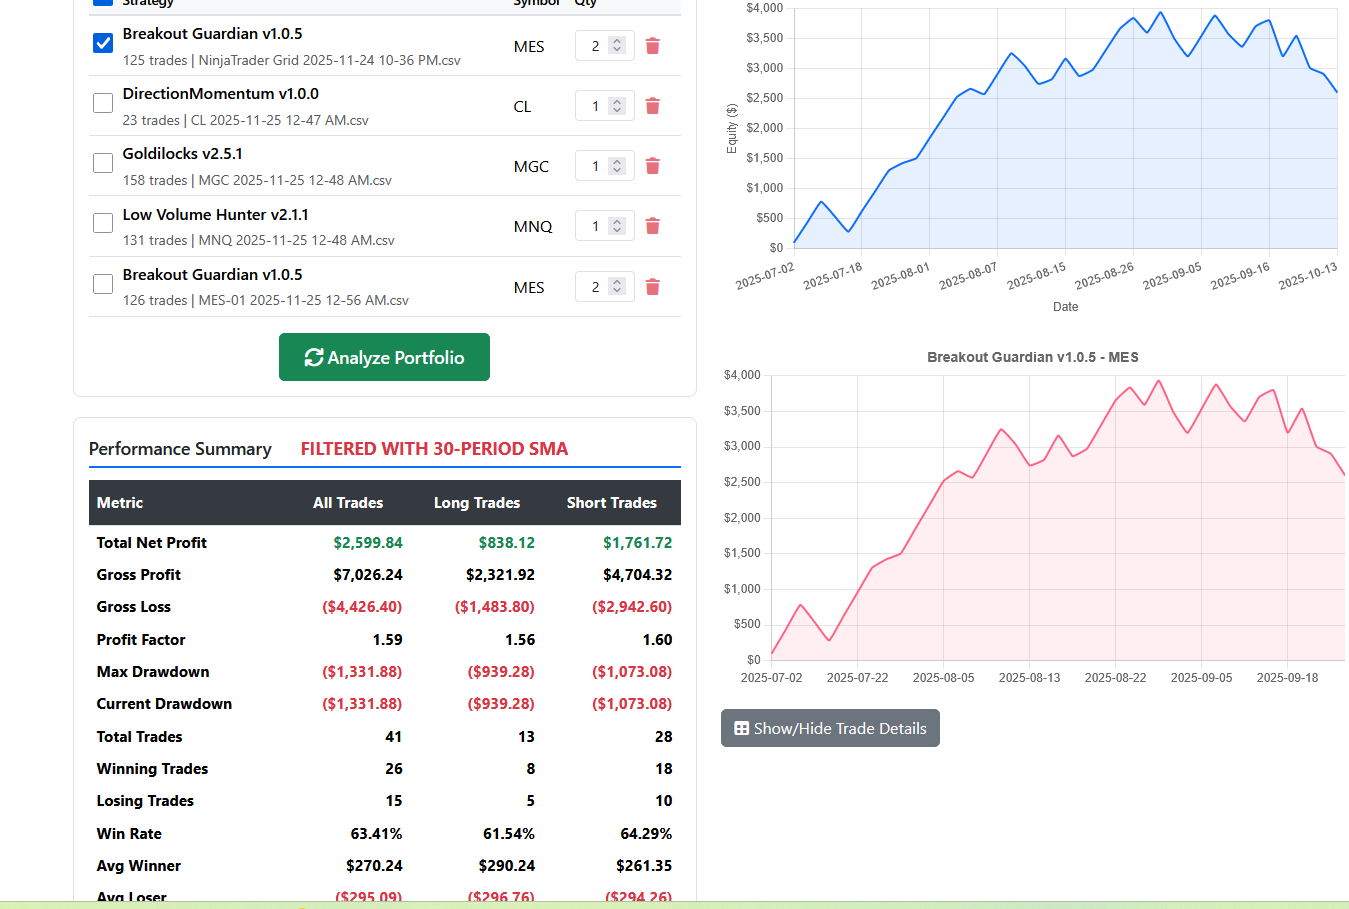
See below for the results I am getting as opposed to the results that I should be able to duplicate within 10% or so, as quoted in another thread.
I also deleted all my data and started again from scratch.
I would really appreciate any help or feedback that will get me closer to duplicating same results.
If I put all my results together I get $5847 vs $19899 off the website results.
OK, I just realized 2 of the strategies may not have enough trades to apply the MA properly, fair enough. But interestingly with goldilocks I get 89 vs 88 trades after appyiing the MA, but then I get -$340 vs $5374.
Any help or suggestions would be appreciated.
Thanks.
Just ran the whole YTD, I get $25986 vs $60447? Am I missing something??
 +