What happened:
When I added today's trade data, the current drawdown suddenly dropped from -$102 to just -$1.02. That seemed too good to be true - and it was.
The problem was that Low Volume Hunter (LVH) had two profitable trades today that pushed its equity back above the 30-period SMA. The old calculation was including those trades in the filtered results because LVH was "above the SMA" after the trades completed.
But here's the issue: LVH was in SIM mode at market open today.
At the end of yesterday, LVH's equity was below its SMA, meaning you would have had it in SIM mode and wouldn't have taken those trades. The profitable trades today shouldn't count in the filtered performance because you wouldn't have been live to capture them.
The fix:
The SMA filter now correctly uses the status from the end of the previous trading day to determine whether to include a day's trades. This matches how you'd actually use the system:
- Check the SMA status at end of day
- Set LIVE or SIM for the next trading day based on that status
- Any trades the next day are included or excluded based on that decision
Yes - and the corrected numbers are actually even more impressive for demonstrating the value of the SMA filter.
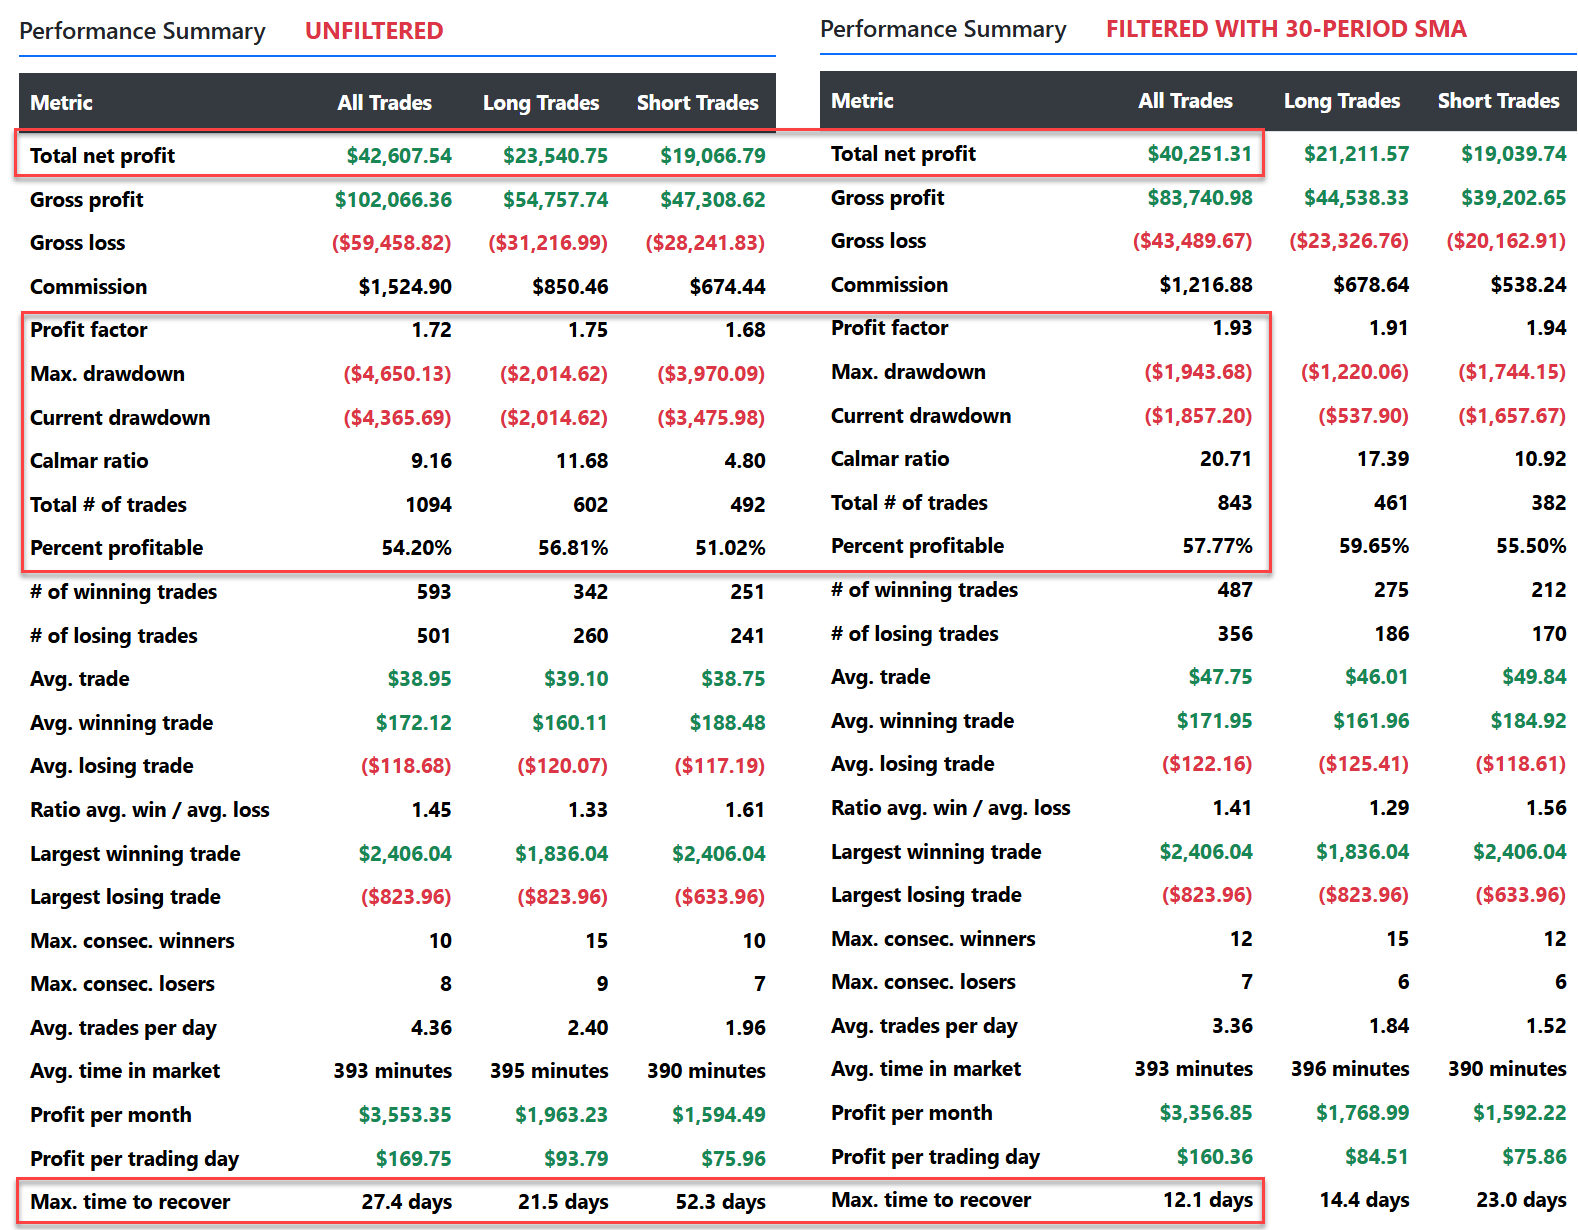
Here's the side-by-side comparison (All Time data, 30-period SMA):
Risk Reduction:
- Max Drawdown: $4,650 → $1,944 (58% reduction)
- Current Drawdown: $4,366 → $1,857 (57% reduction)
- Max Time to Recover: 27.4 days → 12.1 days (56% faster)
- Max Consecutive Losers: 8 → 7
- Calmar Ratio: 9.16 → 20.71 (126% better risk-adjusted returns)
- Win Rate: 54.20% → 57.77%
- Average Trade: $38.95 → $47.75 (23% larger)
- Profit Factor: 1.72 → 1.93
- Net Profit: $42,608 → $40,251 (-5.5%)
- Total Trades: 1,094 → 843 (skipping 251 trades)
By skipping 23% of the trades (the ones during losing streaks), you give up only 5.5% of profit but cut your drawdown by 58% and more than double your risk-adjusted returns.
The SMA filter keeps you out during the rough patches and lets you participate during the good ones. That's the diversified portfolio approach working exactly as designed.